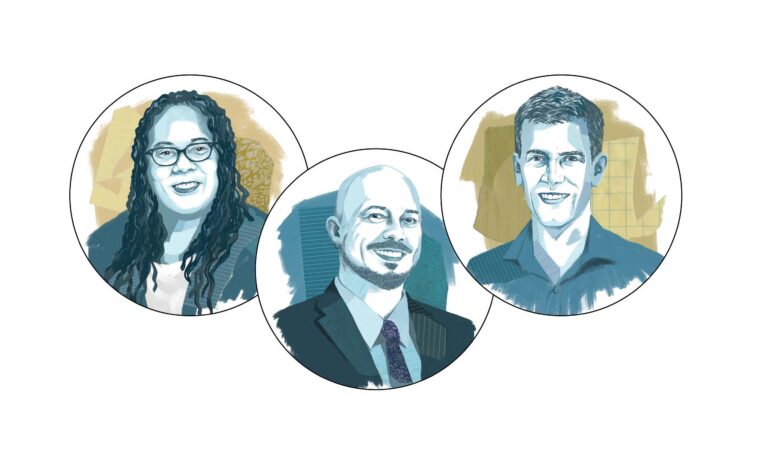
Concerns about living costs are weighing on many Americans, as reflected in a Harris Poll last summer that found 95 percent of adults in the United States believe the country is experiencing an “affordability crisis.” As those concerns have grown, scrutiny has fallen on Americans’ single biggest expense: housing. How well is the housing market serving people in this country, whether that’s hourly workers focused on making the rent, couples in their 20s and 30s hoping to purchase their first home or those with long-term mortgages wanting to move on after years in the same home or condominium? Marquette happens to be an excellent place to ask these types of questions, with disciplines such as real estate, political science, law and more all serving as sources of faculty expertise on topics ranging from real estate economics to housing policy and property law. Marquette’s Vieth Institute for Real Estate Leadership, established in 2024, even brings together experts and resources from business, law and engineering to support leadership in the field and applied, experiential learning. So, when we gathered faculty members from three diverse fields for a panel discussion on housing, they were eager to share insights and solutions.
How well is the housing market serving working people in America today?
Dr. George Cashman: I think it’s doing the best it can right now. We’re in a weird situation. The costs of building a house are rising. Lumber is going up because of tariffs and other issues. It’s harder to find workers to put up homes. … And for people who currently have a house, there are still a lot of people who are locked in with low rates. They say, “I can’t afford to move because I refinanced when rates were around 3 percent, and they’re much higher now.” The supply is having a hard time catching up with demand because few are willing to put their house on the market — and because it’s expensive to build new homes or new apartments.
Kali Murray, J.D.: I agree with George that we have both a supply problem and a demand problem, in the classic sense of the phrase. We’ve gotten locked into thinking about housing as bigger. Entry-level housing in the 1940s and ’50s was between 1,200 and 1,500 square feet, whereas now it’s closer to 2,000 square feet. So, as we need more new housing, we have an idea of physical housing infrastructure that is relatively limited. That is a real problem within the market. Another is that our financing model may not be sufficient for how people enter into the market.
Dr. Matthew Mleczko: It’s an interesting question because I’m not convinced that we have a housing market designed for regular working people. Instead, it is largely designed to maximize property values. And by that measure, it’s astoundingly successful. We have record housing prices, record rents. Unfortunately, the flip side is we have record levels of unaffordability, a huge supply problem. We have record levels of homelessness, of rent burden and housing instability. These things all move in lockstep. The median age of a first-time homebuyer is near 40. So, if you’re now a homeowner, in many places, that’s great. If you are an aspiring homeowner or renter, it’s almost never been worse. As a political scientist, what I’m getting at is we have a political problem when it comes to housing. It’s a solvable problem, but it first requires us to recognize how we all play a part in this.
Let’s dig deeper into the challenges and what’s causing problems in the market.
KM: One way to think about it is that you have two paradigms for understanding property. The first is real property: the idea that ownership of a house or some type of property is a key element of democratic participation. This frame of understanding may narrow how we understand the issues confronting the market, which Matt just pointed out. Another framework that is helpful is to see the issue as a shelter problem rather than a real property problem. We’ll then understand housing in terms of people’s ability to live in a space in a range of ways, through ownership, through renting, through cohousing. Then, we start to understand the market as a housing market and not a real property market. It helps clarify the types of affordability issues that we have.
MM: I’ll build off those great points, as I go a little broader. We have a lot of specific problems, but we have this fundamental contradiction at the heart of our housing policy. We want housing to be affordable, but we also want it to make us rich. And it just cannot do both. That drives a lot of policymaking and which policies and programs win out. For instance, we’ve all pointed to a supply problem. Well, it becomes very difficult to build new, more diverse, more affordable types of housing when many neighborhoods reject that kind of housing. They think it will reduce their property values. There is a lot of empirical evidence that suggests that’s not true, but that’s the perception. This points to a fundamental problem. If housing is meant just to maximize property values — and we have a long tradition of that in the U.S. — then that works directly against this idea of adding to the supply of more sustainable, diverse, affordable types of housing. It also butts up against the idea of ensuring that everyone can pay their rent, of bringing prices down or at least leveling them so that it works for as many people as possible. We spend a lot more money subsidizing homeownership than we do low-income housing and housing assistance. If you have a mortgage, you almost certainly live in subsidized housing. All of these things should get us to rethink how we are spending our dollars and how we could do that in a more equitable way.
GC: I think you’re both kind of right. We have a fundamental disconnect in answering “Is a house housing or is it a financial asset?” And we have seen people treating their houses as financial assets. It is a major way of accumulating wealth. For most people with wealth in the economy, it’s the biggest investment they will make. Unless you fundamentally change the whole system, you’d be asking people to walk away from a lot of their nest eggs. That’s a big change.
How do you address this housing problem? What could help the situation?
MM: There’s no one solution, no silver bullet in housing. But I’ll give three things we can think about.
The first would be difficult politically, but we could do it in the near term. I mentioned the fact that we spend more money subsidizing homeownership than we do low-income housing assistance. That is an easy way to conceptualize the tradeoffs we make. We spend about $30 billion subsidizing homeownership through mortgage interest deduction. Homeowners can deduct the interest — their mortgage interest payments — from their taxes. That advantages folks who have already made it into homeownership, who are largely going to be more affluent than the average citizen or average resident. So, it’s a reward for people who’ve already made it into homeownership and have been able to get over all those upfront barriers like down payment requirements. For $30 billion, we could also dramatically expand the Housing Choice voucher program to make dramatic reductions in evictions, homelessness, housing instability — almost overnight. Only about one-in-four people who qualify for that Housing Choice voucher get it. So, with that $30 billion, we could instead move toward low-income housing assistance. And it would make a big difference in making sure that people have a roof over their head. Economists and other researchers have looked at that mortgage interest deduction and found it doesn’t do a whole lot to improve or increase homeownership rates. So that’s a decision we can make in the near term.
Another thing we could do is think more about different kinds of housing, particularly shared-equity housing, that help us thread the needle that George was getting at — where we don’t necessarily have to throw the baby out with the bathwater. We can still have people earn some equity in their homes, but that equity is capped and reinvested into a community of homes that a nonprofit organization would own. And that keeps home values reasonably steady, so that the next family or next person can come in and benefit from that. And people still earn some equity. They still obtain a foothold into homeownership. So that’s another benefit. And then the third: We should think about the level of government at which we set the housing policies that largely determine the makeup of our communities — in terms of what can be developed, zoning and land-use policies, and transportation policies. There’s a good case that we should do that at a regional level instead of locality by locality. It gets over these incentives to be myopic in our vision — this idea that “you can’t build that here because this is our fiefdom.” And it could do a better job of making sure that we have an adequate housing supply for everyone who needs it. So, those are three things to think about.
KM: So, we accept that housing is a continuum. We need public housing. We need government-subsidized public housing, which is a very controversial proposition in the real estate market because of the idea that government-supported public housing failed. But I always say to people: Government public housing wasn’t intended to be a lifelong commitment to live in government public housing. In the 1930s, ’40s and ’50s, it was considered an entry-level way into the housing market. I often give the example of my grandmother whose very first house outside of her parents’ house was public housing. Within five-to-six years, she had purchased a home. So, as a policy, there could now be public housing that gives you one-to-five years. You establish a trust savings account while you’re there. Part of it goes to the rent in the public housing and part of it goes to establish a down payment for a future home. In doing so, you give people a way to enter into the market.
From a financing perspective, it’s very difficult to enter the market. You need to think about how to get people into the market. One way that Matt mentioned is through cooperatives. But it’s also important to have the right kind of housing. We could actually create public housing that people want by including more bedrooms. Typically, an apartment complex may have 40 units. Instead, you might design a complex with 20 units, each with a third bedroom. That actually fits the need of most entry-level working-class families. And it can be created so you go in knowing you have a five-year lease. At the end of that five-year lease, you’re going to have to get into the market and buy a house. And you do that by forcing savings. That’s a good way of approaching that set of issues.
Another thing to think about are the federal bureaus that are there to help entry-level people obtain financing: the Federal Housing Finance Agency and the Consumer Financial Protection Bureau. These agencies make policy about financing options for poor and working-class people. And when we have an administration that is not laser focused on financing in this market, it is a problem for the market.
The Consumer Financial Protection Bureau was there, for instance, to rewrite and make clearer the HUD-1 statement that people must complete when they purchase a house. That was one of the first things the bureau did after the 2008 financial crisis. Rich people understand mortgage documents and loan documents. And if they don’t understand those documents, they have lawyers who can help them understand those documents. Part of what we did with all the financing reform in the 2010s was working to make the financing market more accessible to a wider range of people. But is that commitment still there? There needs to be a more concentrated, accepted effort to help people understand the range of housing financing options available to them. But we don’t have an agency right now that is issuing financing advice to poor, working class and middle-class people. That was the whole point of the Consumer Financial Protection Bureau. That is a problem we probably have to address.
GC: I like the ideas that you both talk about, but I think the ability to pull them off requires either political change or a fundamental change in how society views housing. It’s hard for our country to work together on those things.
I think the best solution we have that’s most applicable would be some kind of force increasing supply. California is trying to do it, which is similar to what Matthew said about regional requirements. It’s where the state comes in and says you have to do these things, and if you don’t, I’m going to fight it tooth and nail
You also need to try to find ways to lower the costs because housing financing reflects developer risk. If you’re a developer, you often only get financing if you move to the higher end of the marketplace because that’s what banks are willing to finance. They get paid back and that covers the risk associated with doing anyone’s developments. When you plan to do a development and you buy a plot of land, you don’t know what you can put on. You wind up constantly discussing with the community and local government about how many houses you can build, what extras to put in, and it keeps changing. So, you don’t know what you’re going to be able to build, how many units you can put on the marketplace and when it’ll all be done.
That involves more and more risk. Risk and return are related. The higher the risk, the more you need to get paid back, which pushes developers and banks to the higher end of the market.
To address that cost issue with housing for moderate income, does that mean subsidies?
GC: That would be one way. But that requires major political will that I don’t see happening right now. Matthew wants to jump in.
MM: I was just going to say: I think George is right and building that political will is that difficult. It’s going to be my life’s work to figure out how to do that. I see the challenge.
And to Kali’s point, for sure, I am of the opinion that we can achieve all the reforms we can and make a lot of progress, but we’re never going be able to build (market-rate) housing to house the lowest-income folks in the country. Most people do not understand how much development costs. It is very, very costly. So, at some point, the government needs to step in and help subsidize housing, social housing, and there’s plenty of countries that do it. That doesn’t mean we can’t. It is, again, a political problem, and that’s why I put forth the shared-equity programs, because I think it can help us get out of the very bad perception that public and social housing has in this country. It’s a huge political problem that’s very racialized. And we’re not at a point where people are ready to support major investments in all of that. But if we can move in the direction and remind people of what housing is, can and should be through steps like shared-equity housing, I think that’s part of getting us back to that point.
GC: I’ll build on that quickly. We’re all assuming something; I’ll put it out there: People should be housed. That’s the assumption we’re making. I am not convinced that is the viewpoint of most people in this country. I don’t think most people in this country view housing as a right, something everyone is entitled to. It is seen as a reward you earn for working hard and thriving in the marketplace. That’s based in part on my example of Marquette students over the years. I do my section on evictions. These are questions we ask. Even after students talk to a Jesuit priest and read about redlining and read Matthew Desmond’s book Evicted, there is a big split over whether housing is a right you should have as a human being or a reward.
KM: To talk about eviction and landlord-tenant law, that relates to a point I made earlier. Most landlord-tenant law and evictions are based on a real-property model, which leads us to prize the ownership interest of the landlord in the eviction processes. The law is almost written from the standpoint of what matters is a possessory right between the landlord and the tenant. Our eviction law is incredibly complex for a tenant to navigate and punitive too — “You failed to pay your rent, so we’re kicking you out.” I had a student at Marquette write a great paper this year that asked: Should we move to a model of alternative dispute resolution and negotiation and mediation? That’s because the first thing that happens if there’s a conflict between the landlord and the tenant is the landlord gives a tenant notice and the landlord says, “You have five days to pay your rent. Or you have 30 days to pay your rent. If you don’t, you’re out.”
So, Sophia in her article suggested that we flip that and say the landlord gives you five days and says, “We now have to go to a mediation, and we have to manage our conflict.” That’s a housing approach that presumes that we want to keep people in housing. That means that if there’s a conflict between the landlord and the tenant, the first action is not punitive. We could still have the same eviction processes — 5-day, 15-day and 30-day notices — but the first set of steps would be mediation. And then, you want to only hit the punitive proceeding at 30 days or 40 days. Like you can have a system that balances the rights of the parties in the housing situation as opposed to a punitive real property approach. When we ask whether housing is a property issue or a housing issue, that really changes how you view the set of questions the parties have before them.
I’m interested in your perspective as part of this community. How can Marquette be involved in improving the situation?
GC: The first thing I do in my class: I make students aware of the issue. Most of our students aren’t aware of housing insecurity and how many working people are affected by it. The students are 20 years old. They’ve never thought about this issue. So, we bring in Father Michael McNulty, S.J., a Jesuit priest, who talks about their moral responsibilities and about housing and human rights in ways they’ve never thought about before. They read Matthew Desmond’s book about eviction, and we discuss that. That makes them aware of where we’re starting right now.
Through the Center for Real Estate, we have the ACRE program. It’s designed for developing minority developers in the Milwaukee area. It enrolls non-traditional students. They come in and learn how the development process works and they’ve been very successful preparing people who are now developing around the area.
And I forgot to mention that we have our high school outreach program, MK CRE, where we bring in underrepresented young people onto campus for a week — up-and-coming high school students so they’re aware of the role of and opportunities in real estate. It aims to get them excited about the opportunities. I know a couple of our students from that program have either come to Marquette for real estate majors or have gone on to explore real estate programs at other schools.
KM: The law school is quite active right now in housing and issues right in the city. That’s through our pro bono clinic. The Vieth center is now expanding to include a real estate component at the Law and Entrepreneurship Clinic. We have folks like Teig Whaley-Smith (adjunct associate professor of law) who works on housing cooperatives across the city. He teaches our community development course. We now include faculty like me, and Sarah Fox (associate professor of law) has recently joined our faculty. She does local zoning and environmental law. We have ended up in a really interesting place in the law school.
There is our relationship to the Lubar Center for Public Policy Research and Civic Education and, quite frankly, the real-estate genius that is John Johnson (Lubar Center research fellow). John and I share the same suite. We are always throwing ideas back and forth.
He’ll wander by with a cup of tea and say, “Did you know I’ve created an entire real estate database of all the landlords in the city?” And my reaction is, “What?!!” And he says, “Yeah, I’m cross referencing all these landlords with their housing nuisance violations.” John’s informational database on real estate in the city has been a tremendous resource for shaping debate. In the city, we now have landlord accountability. And a lot of this is being driven by the fact that John created this amazing database.
I think a lot of what is happening at Marquette is this: We’ve had traditional strengths. We have a business school with an incredibly strong set of real estate offerings. The program George mentions, ACRE, is one of the things I always like about our business school and the Center for Real Estate. It’s developing cohorts of diverse real estate parties throughout the city who are active and involved in housing and community issues. That set of cohorts has been tremendous.
I also think a lot about the ways in which the law school historically has had a strong property law- and Wisconsin-focused approach to these types of issues. And that’s only been strengthened by the Law and Entrepreneurship Clinic. I too offer a property and social identity class that looks at the ways in which redlining has shaped the city landscape. So, I think Marquette’s pretty good on the housing part of this dynamic because of its historic strength in real estate law and development.
MM: I’m going to see John Johnson later today, so I’ll let him know he came up in our conversation. John is great. This is a happy part of the conversation where we can point to good things that Marquette is already part of. So, long story short, my answer would be to continue doing the good work that we’re already up to. That’s educating. That is public-facing research that moves the needle and promotes good policy reform. It’s convening — getting people on the same page. If we really think this is a housing crisis, and we really want to solve it, it needs to be a team effort. And the Marquettes of the world play a major role in convening that team.
A couple other things I’ll mention include Marquette taking seriously its role as an anchor institution and inspiring other institutions to act similarly. We do a lot of good work with the Near West Side Partners, just west of campus. That also involves convening and helping to operate the Near West Side Partners organization. But it’s also things like helping to bring investment to neighborhoods that have been hollowed out by disinvestment and flight. It’s developing in a responsible way that doesn’t displace folks who have weathered the storm, so to speak. It’s getting Marquette faculty and staff to think about living and locating in these neighborhoods that could use investment, which helps change the narrative about what life is like in these viable and thriving communities.
And there’s one last thing. We could look even further back to our history. Derek Handley has a book, Struggle for the City, in which he points out that in the Civil Rights movement, UW– Milwaukee and Marquette partnered with the Urban League to help train and sustain Black civil rights housing advocates to combat urban renewal efforts and discriminatory housing policies that are part of Milwaukee’s sordid history. And so, again, we have examples throughout history that we can look to. I would say we need to keep it up and do even more.